How Much Is CMHC Insurance? Premium Rates Explained
Last reviewed:
For eligible home purchases below $1.5 million, federally regulated lenders generally require mortgage default insurance when the down payment is below 20%. A lender may still require insurance with 20% or more down. Most people know it as CMHC insurance, after the Canada Mortgage and Housing Corporation, the largest insurer. The cost is a one-time premium worked out as a percentage of your mortgage, and on a typical first home it can add $10,000 to $20,000 to what you borrow. This guide shows the current premium rates, how the premium is calculated, when it applies, and the provincial tax some buyers pay on top. To see how the premium changes your monthly payment, use the Canada mode in our mortgage calculator.
How Much Does CMHC Insurance Cost?
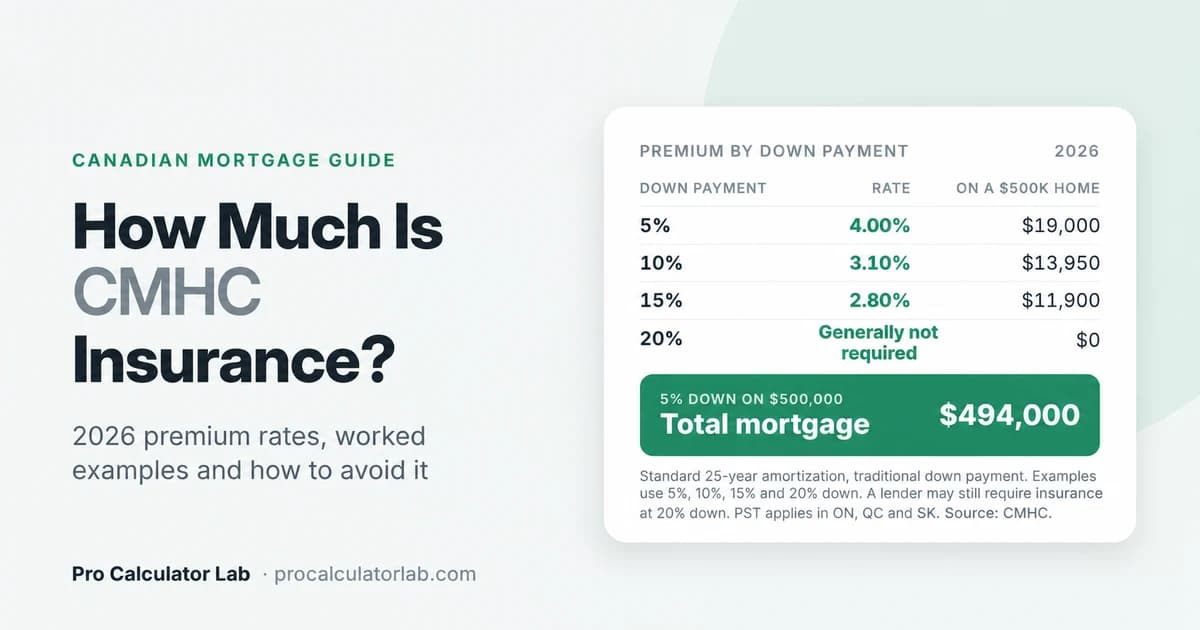
CMHC insurance costs between 2.80% and 4.00% of your mortgage amount for most buyers who put down less than 20%, using standard 25-year amortization and a traditional down payment. The smaller your down payment, the higher the rate: 4.00% with 5% to 9.99% down, 3.10% with 10% to 14.99% down, and 2.80% with 15% to 19.99% down.
The premium is paid once, when the mortgage is funded. Most buyers add it to the mortgage rather than paying it upfront, so it is repaid with interest over the life of the loan.
What Is CMHC Insurance?
CMHC mortgage loan insurance, also called mortgage default insurance, protects the lender, not you, if you stop making payments. In exchange, lenders can offer mortgages with as little as 5% down, often at lower interest rates than uninsured loans because the risk to the lender is smaller.
CMHC is a federal Crown corporation, but it is not the only insurer. Sagen and Canada Guaranty also provide mortgage default insurance, and their premiums are generally similar. Your lender chooses the insurer; you do not usually pick it yourself.
When Is Mortgage Default Insurance Required?
- Down payment below 20%: for eligible home purchases below $1.5 million, federally regulated lenders generally require mortgage default insurance when you borrow more than 80% of the purchase price. A lender may still require insurance with 20% or more down.
- Purchase price below $1.5 million: since December 15, 2024, insured mortgages are available on eligible homes priced below $1.5 million (the cap used to be $1 million). Homes at $1.5 million or more need at least 20% down and cannot be insured under the standard homeowner purchase program.
- Amortization up to 25 years, or 30 years for some buyers: eligible first-time buyers and buyers of newly built homes can choose a 30-year insured amortization through CMHC Home Start, subject to its program conditions.
- Owner-occupied: standard homeowner insurance is for eligible homes occupied by the borrower or a qualifying related person, subject to the insurer's requirements.
- Minimum down payments still apply: 5% of the first $500,000, plus 10% of the portion above $500,000 for eligible homes priced below $1.5 million. On a $750,000 home, that is $25,000 + $25,000 = $50,000 (about 6.7%).
CMHC Premium Rates by Down Payment (2026)
The premium rate depends on your loan-to-value ratio (LTV), which is the mortgage amount as a share of the purchase price, before the premium is added.
| Down Payment | Loan-to-Value (LTV) | Premium on the Mortgage |
|---|---|---|
| 35% or more | Up to 65% | 0.60% |
| 25% to 34.99% | 65.01% to 75% | 1.70% |
| 20% to 24.99% | 75.01% to 80% | 2.40% |
| 15% to 19.99% | 80.01% to 85% | 2.80% |
| 10% to 14.99% | 85.01% to 90% | 3.10% |
| 5% to 9.99% | 90.01% to 95% | 4.00% |
| 5% to 9.99%, non-traditional down payment (e.g., borrowed) | 90.01% to 95% | 4.50% |
The first three rows apply only if a lender asks for insurance on a mortgage with 20% or more down, which is uncommon for individual buyers. For eligible CMHC Home Start insured mortgages with amortizations over 25 years and up to 30 years, an additional 0.20 percentage points applies: the standard 2.80%, 3.10% and 4.00% rates become 3.00%, 3.30% and 4.20%; the non-traditional down-payment rate becomes 4.70%. First-time-buyer or newly built-home eligibility and other program conditions apply.
Our calculator does not currently model insured amortizations over 25 years or their premium surcharge.
Source: CMHC Purchase premium schedule
Source: CMHC Home Start eligibility and premium schedule
How CMHC Insurance Is Calculated: Example
Say you are buying a $500,000 home with 5% down.
- Down payment: $500,000 × 5% = $25,000.
- Mortgage before insurance: $500,000 − $25,000 = $475,000.
- Loan-to-value: $475,000 ÷ $500,000 = 95%, so the premium rate is 4.00%.
- Premium: $475,000 × 4.00% = $19,000.
- Total mortgage if the premium is added: $475,000 + $19,000 = $494,000.
Same Home, Different Down Payments
| Down Payment on $500,000 | Mortgage | Premium Rate | CMHC Premium | Total Mortgage |
|---|---|---|---|---|
| 5% ($25,000) | $475,000 | 4.00% | $19,000 | $494,000 |
| 10% ($50,000) | $450,000 | 3.10% | $13,950 | $463,950 |
| 15% ($75,000) | $425,000 | 2.80% | $11,900 | $436,900 |
| 20% ($100,000) | $400,000 | Generally not required | $0 | $400,000 |
Going from 5% to 10% down cuts the premium by more than $5,000, and reaching 20% generally avoids the high-ratio insurance requirement. A lender may still require insurance with 20% or more down.
Paying the Premium Upfront vs Adding It to Your Mortgage
You can pay the premium in cash at closing, but most buyers add it to the mortgage. That is easier on your savings, but you pay interest on it.
In the 5% down example, adding $19,000 to the mortgage at a 5% fixed rate over 25 years raises the monthly payment by about $110 (from $2,762.62 to $2,873.13) and adds approximately $14,151.48 in interest over the full amortization, assuming the 5% rate remains unchanged throughout 25 years. You can compare both versions in our mortgage calculator, which applies Canadian semi-annual compounding. For the formula behind those payments, see how a mortgage payment is calculated.
Provincial Sales Tax on CMHC Insurance
GST and HST do not apply to mortgage insurance premiums, but three provinces charge their own sales tax on them:
| Province | Tax on the Premium | On a $19,000 Premium |
|---|---|---|
| Ontario | 8% | $1,520 |
| Quebec | 9% | $1,710 |
| Saskatchewan | 6% | $1,140 |
Quebec’s insurance-premium tax increases to 9.975% for premiums paid after December 31, 2026.
This tax cannot be added to the mortgage. It is usually collected by your lawyer or notary at closing, so include it in your closing-cost budget along with legal fees, land transfer tax and adjustments. For more on how sales taxes differ by province, read GST vs HST in Canada.
How to Lower or Avoid CMHC Insurance
- Save 20% down. With a conventional mortgage (80% LTV or less), the high-ratio insurance requirement generally does not apply, although a lender may still require insurance.
- Move up a tier. Even moving from 9% to 10% down changes the standard rate from 4.00% to 3.10% on the whole loan.
- Use eligible savings programs. A First Home Savings Account (FHSA) or the RRSP Home Buyers' Plan can help you build a larger down payment.
- Choose 25 years over 30 if the payment works for you, to avoid the Home Start premium surcharge and pay less interest overall.
- Consider the price. A slightly less expensive home can push your down payment into a lower premium tier.
Frequently Asked Questions
Is CMHC Insurance a One-Time Fee?
Yes. The premium is charged once, when the mortgage is funded. If you add it to your mortgage, you repay it gradually through your regular payments.
Can I Get CMHC Insurance Refunded?
Generally no. The premium is not refunded if you pay down the mortgage early or later reach 20% equity. Eligible borrowers may receive a 25% partial premium refund through CMHC Eco Plus or Eco Improvement, subject to program conditions.
Portability is separate from a cash refund. If you move and port your mortgage insurance to an eligible new home, the insurer may apply portability benefits or a premium credit toward the new insurance premium, subject to its rules. Ask your lender how this applies to you.
Does CMHC Insurance Protect Me If I Cannot Pay?
No. It protects the lender. If you are worried about losing income, mortgage life or disability insurance is a separate, optional product.
How Much Is CMHC Insurance on a $400,000 Mortgage?
It depends on your down payment and eligibility. Under the standard premium schedule, at 4.00% (5% to 9.99% down) the premium is $16,000; at 3.10% it is $12,400; and at 2.80% it is $11,200.
Do I Need CMHC Insurance for a Home Over $1.5 Million?
No. Homes priced at $1.5 million or more need at least 20% down, and mortgages on them cannot be insured under the standard homeowner purchase program.
Sources
CMHC: Mortgage loan insurance premium rates and provincial tax treatment
Finance Canada: Mortgage reforms effective December 15, 2024
FCAC: How much you need for a down payment
nesto: Provincial sales tax on mortgage default insurance
Ontario Ministry of Finance: Insurance and benefits plans
Revenu Quebec: Insurance-premium tax rate change after December 31, 2026
Saskatchewan: PST-73, insurance contracts
CMHC: Eco Plus and Eco Improvement premium-refund programs
CMHC: Mortgage loan insurance portability
This article is general information, not mortgage, tax or legal advice. Premiums, rules and eligibility are set by insurers and governments and can change; confirm with your lender before you buy.